Ready to get started?
Easily integrate next-generation payments and financial data into any app. Build powerful products your customers love.
SHARE ARTICLE


 Share link copied!
An SMS payment is a payment a customer makes by tapping a link you have sent them by text. That is the whole mechanism: no app for the customer to install, no card machine, no card number read down the phone. The business creates a request for a set amount, the customer opens the text, and the money moves from their bank account or card to the business’s account with a confirmation on both sides. The phrase has an older meaning too, and it is worth clearing up first, because half of what Google returns for it is about the wrong thing.
The two things “SMS payment” means
Carrier billing, sometimes called premium SMS, is when a person texts a keyword to a shortcode and the cost is added to their mobile phone bill. It exists for charity donations, ringtones and app purchases, it is run by the mobile networks, and it is not a way for a business to collect payment for goods or services; the amounts are capped, the network keeps a large share, and the customer’s bank is never involved.
Text-to-pay, or pay by text, is the business method: a payment link delivered by SMS. The customer taps it and pays in the browser, in their Bank app, or with a card. Everything on this page is about that.
How an SMS payment works, step by step
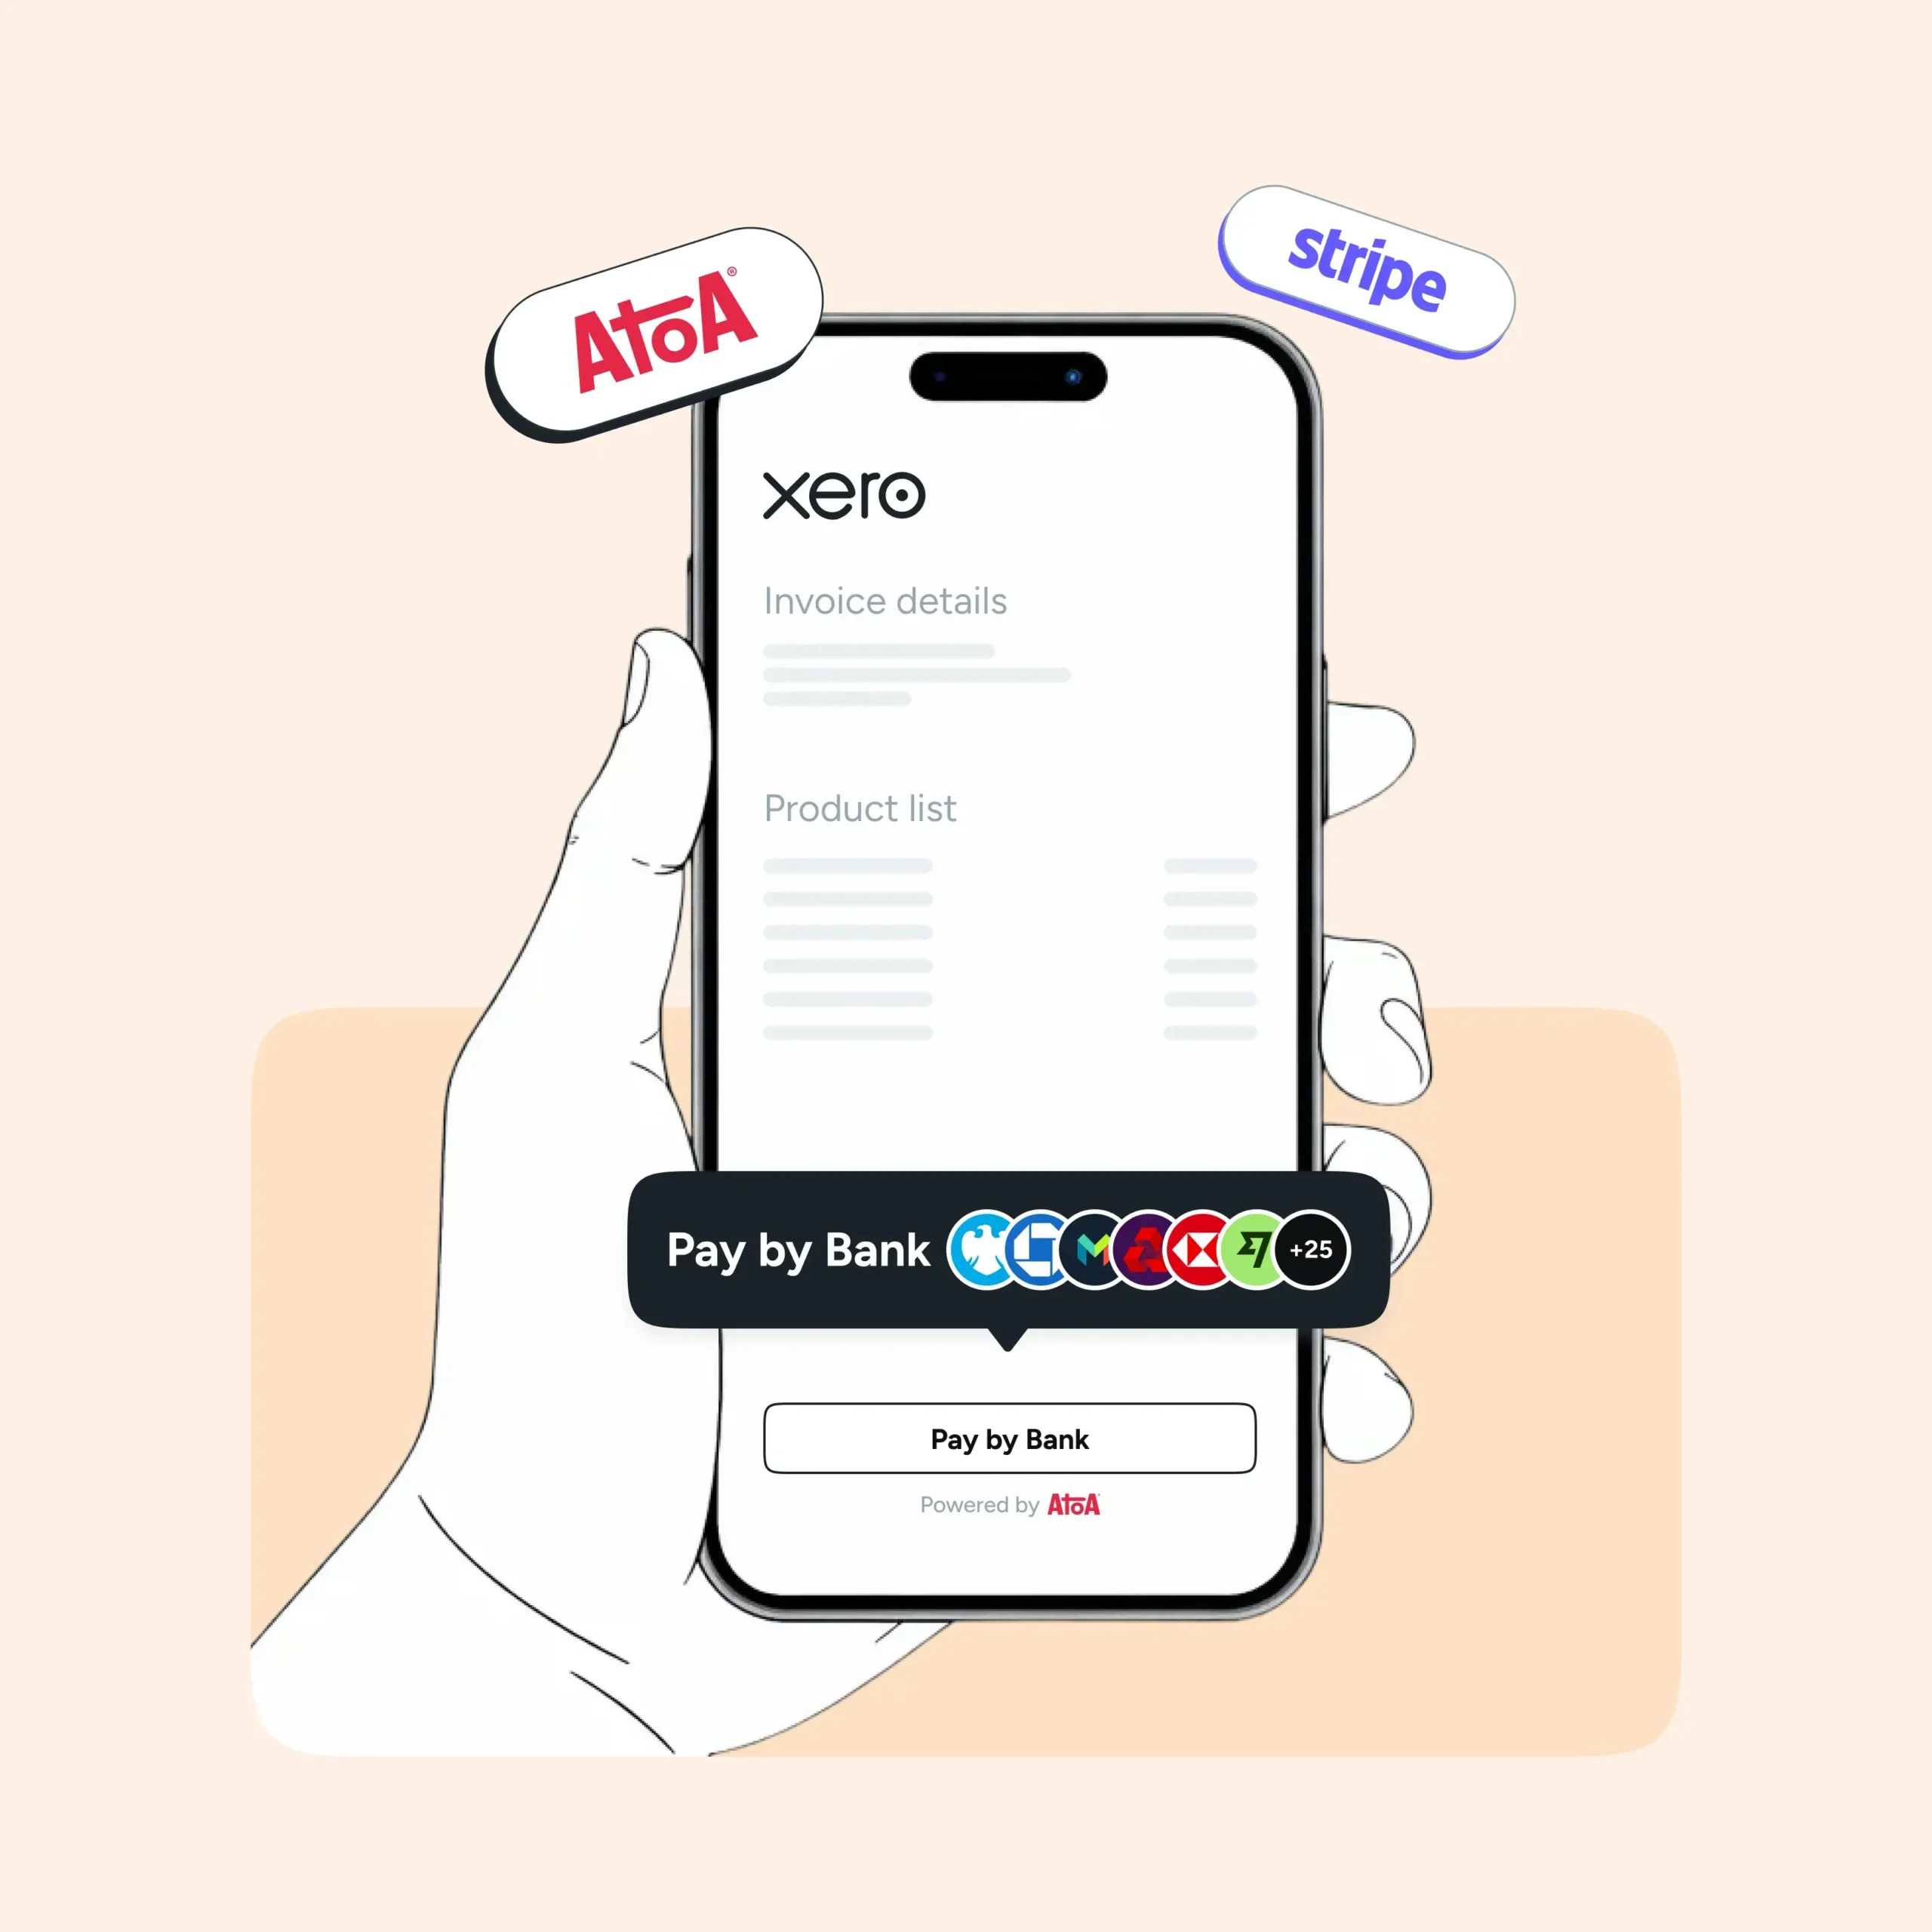
The business creates a payment request in its provider’s app or dashboard, entering the amount and, ideally, a reference the customer will recognise (an invoice number, a booking date, a vehicle registration). The provider generates a unique link for that request. The business sends it by text, and with Atoa also by WhatsApp or email from the same screen, to the customer’s number. The customer’s phone shows a message with the business name, the amount and the link. They tap it. If they choose Pay by Bank, their Bank app opens with the payee and amount already filled in and they approve with Face ID, a fingerprint or a passcode, which satisfies Strong Customer Authentication; the money moves over Faster Payments and the business sees it as paid within seconds. If they choose card, they enter their card details on the secure page themselves and the card is charged. Either way the payment lands in the business’s dashboard against the reference, and syncs to Xero, QuickBooks or Sage if the business has connected them.
What the business never does in that sequence is handle payment details. That is the difference between a text link and the alternative it replaces.
What it replaces: card details over the phone
Before payment links, a remote payment meant asking the customer to read out their card number while a member of staff keyed it into a terminal or virtual terminal. The card schemes classify that as a MOTO transaction: card-not-present, not authenticated by the cardholder, and therefore out of scope of Strong Customer Authentication under the Payment Services Regulations 2017 (Visa’s summary of the FCA position). The fraud and chargeback liability sits with the merchant, the keyed rate is priced accordingly (Square, for example, publishes 2.5% for manually entered payments against 1.75% in person), and PCI DSS puts the card numbers on your call recordings and notepads in scope. Atoa does not offer MOTO; the text link is the route. Our guide to taking card payments over the phone sets out the MOTO rules in full.
How to set up SMS payments for your business
Choose a provider that issues payment links and lets the customer pay by bank as well as by card from the same link; with Atoa, a UK registered business signs up online, passes the usual checks, and can send its first link from the app or dashboard the same day, with no terminal to buy and no monthly fee on the Basic plan. Decide who sends links and give them access: reception, the service desk, the accounts team. Set the text template so every message carries the business name, the amount, the reference and what the payment is for. Connect accounting software so payments post against invoices without re-keying. Then tell customers to expect it: a line on the quote, the booking confirmation or the invoice that says “we’ll text you a secure link to pay” is the single biggest lift to the rate at which links get paid, because it turns an unexpected text into an expected one. Atoa’s SMS payments page covers the product side.
What the text should say, and why it matters
Banks and the police have spent years telling people not to tap links in texts, so the message has to look like what it is. The sender should be identifiable as the business. The text should state the amount and a reference the customer already knows, and say what it is for. The link should be the provider’s own domain, not a shortened URL. It should arrive when the customer expects it, ideally minutes after the conversation or the invoice. And it should never ask for anything except the payment: no requests to confirm details, no attachments.
On the rules: a payment request sent to a customer about a transaction they have asked for is a service message, not direct marketing, so the consent requirements in the Privacy and Electronic Communications Regulations for marketing texts do not apply to it; the ICO’s guidance is clear that administrative and customer-service messages are outside the definition, provided they carry no promotional content. Put an offer or an upsell in the same text and it becomes marketing, with all that implies. Keep it to the payment.
What SMS payments cost
There is no hardware to buy and, with Atoa, no monthly fee on the Basic plan; the cost is per payment and depends on how the customer chooses to pay. Pay by Bank is from 0.7% + 20p ex VAT, falling with volume. A UK card through the same link is from 1.3% + 20p, with business cards and Amex higher. On a £500 deposit that is £3.70 by bank or £6.70 by card, against £12.50 at a typical 2.5% keyed rate for the same payment taken over the phone, and by bank there is no chargeback exposure on it afterwards. Full rates are on Atoa’s pricing page.
Where SMS payments fit
They fit wherever the customer is not in front of you and the amount is agreed: a deposit to hold a vehicle, a treatment plan, a table or a job; a balance due before delivery or collection; a trade order confirmed on the phone; an invoice that has gone unpaid, where resending the same link by text is a gentler chase than a call; a phone enquiry that becomes a sale. They do not fit an unattended sale where nobody has the customer’s number, an in-store payment where a QR code or terminal is quicker, or a payment above the provider’s per-payment limit (£15,000 with Atoa on Pay by Bank).
When it does not go through
Most failures are the customer’s side and are recoverable. They did not see the text: resend it, or send the same link by WhatsApp or email. Their bank limit blocked a large Pay by Bank payment: split it, or they pay by card from the same link. They do not bank with a UK bank: card. They are wary of the link: confirm the amount and reference on the phone and tell them the sender name to expect. What you should not do is fall back to taking the card number verbally; that reintroduces the MOTO risk the link was there to remove. To see it working on your own payments, book a demo.
Frequently asked questions
What is an SMS payment?
An SMS payment is a payment a customer makes by tapping a secure link sent to them in a text message and paying from their phone, in their Bank app or by card. The business creates the request for a set amount, texts the link and is notified the moment it is paid. It is different from carrier billing, where a purchase is charged to a phone bill by texting a shortcode.
How do I set up SMS payments for my business?
Sign up with a provider that issues payment links, such as Atoa, which onboards UK registered businesses online with no hardware. Create a payment request in the app or dashboard with the amount and a reference, send it by text, WhatsApp or email, and the customer pays by Pay by Bank or card from the same link. Connect Xero, QuickBooks or Sage so payments post against invoices automatically.
Are SMS payments safe?
Yes, when the link is a genuine payment link. A Pay by Bank payment is approved by the customer inside their own Bank app with Face ID, a fingerprint or a passcode, no card details are shared, and the payment cannot be charged back. Make the text recognisable: business name as sender, the amount and a reference the customer knows, the provider’s own domain rather than a shortened link, and tell customers in advance to expect it.
Can a customer pay by card from a text?
Yes. With Atoa the same link takes Pay by Bank or a card, including Visa, Mastercard, American Express, Apple Pay and Google Pay, so the customer chooses at the point of paying and the business does not need two flows.
Is there a free SMS payment system?
There is no monthly fee on Atoa’s Basic plan and nothing to buy; the cost is per payment, from 0.7% + 20p ex VAT for Pay by Bank and from 1.3% + 20p for a UK card. Providers that advertise free SMS payments charge per transaction in the same way.
Do I need consent to text a customer a payment link?
A payment request about a transaction the customer has asked for is a service message, not direct marketing, so the PECR consent rules for marketing texts do not apply to it, per ICO guidance. Keep the text to the payment; adding an offer or promotion turns it into marketing.
Sources
- Information Commissioner’s Office, Identify direct marketing (service messages)
- Visa, Strong Customer Authentication: out-of-scope and exempt transactions (FCA position on MOTO)
- Square UK, pricing (2.5% manually entered; 1.75% in person)
- Atoa, SMS payments, pricing and Pay by Bank pages
SHARE ARTICLE
Share link copied!