Ready to get started?
Easily integrate next-generation payments and financial data into any app. Build powerful products your customers love.
SHARE ARTICLE


 Share link copied!
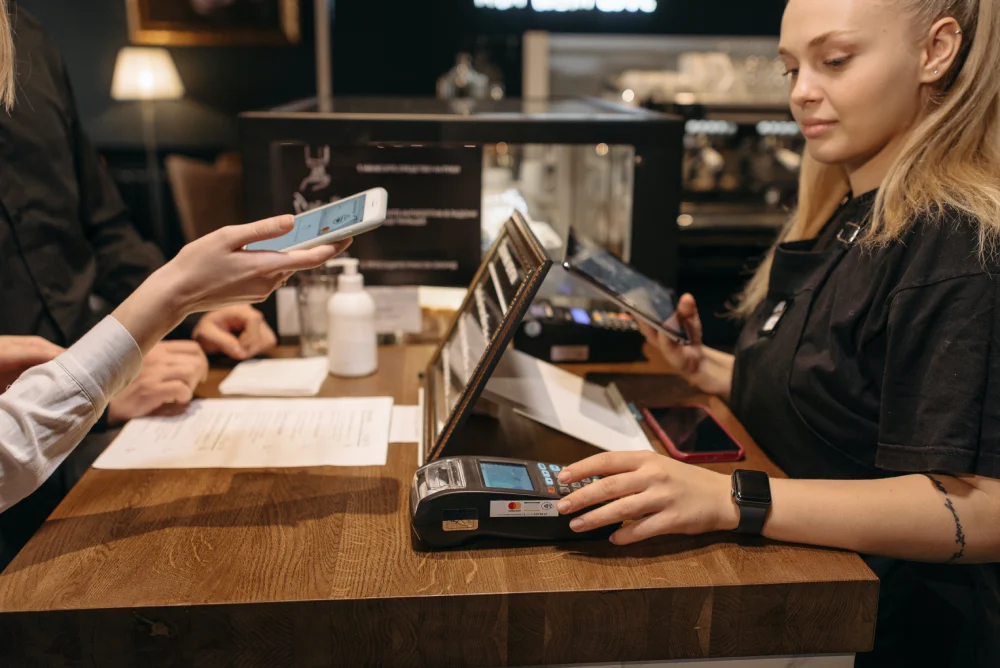
Watch the queue at any busy counter and most customers pay the same way: they hold a card, a phone or a watch near the card machine, wait for the beep and go. Each of those taps is an NFC payment. For a business, accepting NFC payments takes a card terminal that can read contactless cards and phones, an account with a payment provider that processes the payment, and a WiFi or mobile data connection for the terminal to send it for approval.
It is now the ordinary way to pay in person in the UK. UK Finance counted 18.9 billion contactless payments in 2024, 39% of every payment made in the country, and for the first time half of all UK adults paid with a phone or other device at least once a month. This page covers what a business needs to take those payments, what changed when the FCA removed the fixed £100 contactless limit on 19 March 2026, and what NFC acceptance costs on the rates UK providers publish, worked through a real month for a three-site business.
If you came here to switch NFC on in your own phone, Google explains the Android settings in its Wallet help and Apple explains the iPhone side in its guide to setting up Apple Pay. Everything below is for a business taking payments from its customers.
What NFC payments are, in a business’s terms
Near-field communication (NFC) is a short-range radio standard maintained by the NFC Forum, the industry body behind it. It works at a base frequency of 13.56 MHz over a typical range of up to 2 cm, which is why a customer holds their card or phone right up to the terminal rather than waving it from across the counter. NFC devices are built to work with readers and cards made to the ISO/IEC 14443 contactless standard, and when a phone pays, the NFC Forum points out that the reader only needs to see something that behaves like a card. That is why one terminal reads a plastic card, a phone and a watch in the same way.
The NFC Forum defines several operating modes, and two of them meet at your till. In card emulation mode, which the Forum calls the most common today, the customer’s phone or watch acts as a contactless bank card. In reader mode, a device reads contactless cards and tags, which is the job your terminal does. A third mode, peer-to-peer, is for two devices swapping data such as contact details.
Phones matter more every year. UK Finance found that 57% of UK adults were registered for a mobile payment service in 2024, up from 42% the year before and rising to 88% of 16 to 24-year-olds, and it says phone taps now appear to be replacing taps with a physical card. Terminals built for EMV contactless accept contactless cards and mobile wallets such as Apple Pay and Google Pay alike, so the practical question for a business is not whether to take phone payments but which terminal, provider and price to take them on.
How a tap becomes a payment
An NFC card payment at a counter runs through five steps.
- You enter the amount and the terminal waits for a card or device.
- The customer holds their card, phone or watch against the contactless symbol. On an iPhone they confirm with Face ID, Touch ID or a passcode first, unless the card is set to Express Mode.
- The card or phone sends a payment credential with a security code generated for that transaction alone. An iPhone sends a device-specific number created by the customer’s bank, never the card number itself.
- The terminal passes the payment through your provider and the card network to the customer’s bank, which checks the code and approves or declines it.
- The terminal shows the result and the payment appears in your dashboard.
Two things follow for a business. The tap is local but the approval is not, so the terminal needs a live connection; the Atoa terminal connects over WiFi or 4G. And because the card number is swapped for a token that EMVCo describes as restricted to a specific merchant, device or payment scenario, a tapped payment exposes far less than card details read out over the phone. Apple adds that neither Apple nor the iPhone sends the actual card number to the terminal.
What you need to accept NFC payments
There are four parts. The first is a terminal that accepts contactless payments and shows EMVCo’s contactless symbol, the mark that tells customers they can tap; UK Finance notes that every bank-issued payment terminal in the UK has been able to accept contactless since January 2020. The second is an account with a payment provider that processes card payments and pays the money out to you. The third is a connection, WiFi or mobile data, for the terminal to reach that provider. The fourth is card-data security under PCI DSS, the card industry’s standard; the Atoa terminal is PCI DSS compliant.
You also choose where the reader lives. A dedicated terminal sits on the counter or goes to the table. The alternative is tap on phone, where software such as Apple’s Tap to Pay on iPhone turns a member of staff’s own handset into the reader; Square, SumUp, PayPal Point of Sale (formerly Zettle) and Dojo all list it on their UK pricing pages. Atoa does not offer tap on phone. Customers tap on the Atoa terminal instead, and if taking payments on your own phone is what you need, our guide to Tap to Pay on iPhone compares the providers that do it. A third route, a QR code, takes the payment without NFC at all.
| Route | How the customer pays | What you need | With Atoa |
|---|---|---|---|
| NFC card terminal | Taps a card, phone or watch, or inserts a card and enters a PIN | A contactless terminal and a provider account | Yes: PAX A920 Pro, cards from 1.3% |
| Tap on phone (for example Tap to Pay on iPhone) | Taps a card or phone on a staff member’s handset | A compatible phone and a provider’s app | Not offered |
| QR code | Scans a code with their own phone and approves in their Bank app, or pays by card where card payments are enabled | A code on the terminal screen, a stand or a printed sheet | Yes: Pay by Bank from 0.7% |
The contactless limit since March 2026
For years the answer to how much a customer could tap was £100. That figure came from the UK’s Strong Customer Authentication rules: a contactless card payment could skip authentication only if it was £100 or less, and after £300 in total or five taps in a row the card had to be checked with chip and PIN. On 19 March 2026 the FCA replaced those fixed limits with a risk-based exemption. Banks and payment providers with strong fraud controls can now set their own contactless limits, and the FCA is encouraging them to let customers choose a personal limit or switch contactless off.
What that means at your till is that the limit belongs to the customer’s bank, not to you or your terminal, and it can differ from one card to the next. The FCA has said it expects most banks and payment providers to keep their existing limits for the foreseeable future, so there is no sudden change to plan for, but a fixed £100 is no longer the rule. When a payment is over the customer’s limit it falls back to chip and PIN, which is why a card machine still needs a PIN pad; the Atoa terminal is a full chip and PIN machine as well as a contactless one. Customers’ protection has not changed either: if a lost or stolen card is used, their bank must still reimburse them.
What NFC payments cost: published UK rates
The cost has three parts: the terminal, any monthly fee and the rate on every payment, and the rate is the part that grows with your takings. The table sets out what five providers publish on their own UK pricing pages for in-person card payments, checked on 27 September 2026.
| Provider | Published in-person card rate | Terminal | Monthly fee | Tap on phone | Pay by Bank on the terminal |
|---|---|---|---|---|---|
| Atoa | From 1.3% (UK cards, ex VAT) | PAX A920 Pro: £338.30 to buy or £20 a month | Basic free; Growth £79 and Advanced £149 per location (ex VAT) | No | Yes, from 0.7% (ex VAT) |
| Dojo | 1.2% blended below £100,000 annual card turnover; custom rate above | Go Max: £149 upfront (launch offer, listed at £229) or £25 a month | Essential free; Plus £11.99 per location for new customers (listed at £25) | Yes (Tap to Pay on iPhone) | Not shown |
| SumUp | 1.69% pay as you go; 0.99% on Payments Plus, for £3,000 or more a month | Not priced on the pricing page | None on pay as you go; Payments Plus £19 | Yes | Not shown |
| Square | 1.75% (UK cards) | Square Terminal £149 + VAT; Square Reader £19 + VAT | Free plan £0; Plus from £29 | Yes (iPhone and Android) | Not shown |
| PayPal Point of Sale (formerly Zettle) | 1.75% (cards and mobile wallets) | Terminal from £149 ex VAT; Reader from £29 ex VAT for new business users | None | Yes | Not shown |
Two things the table cannot show. Some published rates depend on your size: Dojo’s 1.2% applies only below £100,000 a year of card takings, and SumUp’s 0.99% needs its £19-a-month plan. And beneath every card rate sits interchange, which UK rules cap at 0.2% of the payment for consumer debit cards and 0.3% for consumer credit cards, plus scheme fees and the provider’s margin. Pay by Bank does not use the card networks, which is why it can be priced below them.
A worked month for a three-site business
Here is what those rates come to for one business. Take a café and bakery group with three sites and one terminal in each, taking £75,000 a month in person across 3,000 payments, an average of £25, all on UK consumer cards today. Atoa is priced at its published “from” rates on the free Basic plan, and every other provider at the standard in-person rate it publishes. Hardware is left out because the table above covers it, and every figure is before VAT.
| Provider and published rate | Fees for the month | How it is worked |
|---|---|---|
| Atoa, all by card at 1.3% | £975.00 | £75,000 × 1.3% |
| Atoa, a quarter of takings by Pay by Bank on the same terminal | £862.50 | £56,250 × 1.3% = £731.25, plus £18,750 × 0.7% = £131.25 |
| Atoa, half of takings by Pay by Bank | £750.00 | £37,500 × 1.3% = £487.50, plus £37,500 × 0.7% = £262.50 |
| SumUp Payments Plus, 0.99% + £19 a month | £761.50 | £75,000 × 0.99% = £742.50, plus £19 |
| SumUp pay as you go, 1.69% | £1,267.50 | £75,000 × 1.69% |
| Square, 1.75% | £1,312.50 | £75,000 × 1.75% |
| PayPal Point of Sale, 1.75% | £1,312.50 | £75,000 × 1.75% |
| Dojo | Quoted | £900,000 a year of card takings is above the £100,000 limit for Dojo’s published 1.2% |
On top of the fees, three Atoa terminals cost £60 a month to rent (3 × £20) or £1,014.90 to buy (3 × £338.30). Buying works out lower than renting once you keep a terminal beyond 17 months, since £338.30 ÷ £20 = 16.9.
On cards alone, SumUp’s Payments Plus plan is the lowest published figure at £761.50, Atoa’s card rate comes to £975 and Square and PayPal Point of Sale come to £1,312.50. Atoa’s difference is the second way to pay on the same terminal. Every pound a customer pays by Pay by Bank costs 0.7% instead of 1.3%, 46% less, so moving a quarter of takings saves £112.50 a month, £1,350 a year, and moving half saves £225 a month, £2,700 a year, with no second device on the counter. How many customers choose it depends on how you present it, which is why the table shows two shares rather than promising one.
At £900,000 a year of card takings, the published rate is a starting point. Atoa offers custom pricing above £500,000 of turnover, Dojo sets a custom rate above £100,000 of annual card turnover, SumUp offers bespoke fees from £10,000 a month and Square says custom rates may be available above £200,000 a year. Use the table to test a quote, and ask every provider on your list, Atoa included, to price your real card mix. Our comparison of card machine providers covers contracts, rental and exit fees in more depth.
Taking NFC payments with Atoa
Atoa is an FCA-authorised UK payments platform (FRN 1007647) for established and multi-site businesses, and its card machine is the PAX A920 Pro. It takes contactless and chip and PIN on Visa, Mastercard and American Express, plus Apple Pay, Google Pay and any NFC phone. It has a touchscreen, a built-in receipt printer, USB-C charging and a 5,150 mAh battery, and it connects over WiFi or 4G, so it works at the counter, at the table or on the shop floor. It costs £338.30 to buy or £20 a month to rent, with no long-term contract either way. Card payments start from 1.3% and are provided by Rapyd Payments Limited (FRN 900688); rates vary by card type, business size and average transaction value, and business cards and American Express can cost more.
The same screen also offers Pay by Bank. The customer chooses it, scans the QR code on the terminal and approves the payment in their own Bank app with Face ID, a fingerprint or a passcode. It is not an NFC payment, and that is the point: it costs from 0.7% ex VAT, up to 50% lower than card fees, and it cannot be charged back because there is no card network in the chain to reverse it. The customer can still ask you for a refund, which you send from the dashboard. Each payment is confirmed in seconds and paid out instantly or on the next working day, depending on your settlement setup, and a single payment can be up to £15,000.
Every terminal sits under one account and one dashboard however many tills and sites you run, and where you use an integrated EPOS such as Epos Now, pointOne, Tevalis or Till Tech, the payment closes the sale in the till. Plans run from Basic, which is free, to Growth at £79 and Advanced at £149 per location a month ex VAT, for features such as Google review prompts and custom staff roles, and the pricing page sets out each one. Restaurants weighing up how to accept contactless payments at the table can use the same terminal and QR codes.
To see what your own mix of payments would cost, book a demo and we’ll run the numbers with you, or start a 7-day free trial.
Frequently asked questions
What do I need to accept NFC payments?
You need a card terminal that accepts contactless payments, an account with a payment provider that processes the payments, and a WiFi or mobile data connection for the terminal. Atoa supplies the PAX A920 Pro, which takes contactless cards, Apple Pay, Google Pay and any NFC phone, for £338.30 to buy or £20 a month to rent.
How much does it cost to accept NFC payments in the UK?
It depends on the terminal, any monthly fee and the rate on each payment. On rates published in September 2026, in-person card payments cost 1.75% with Square and PayPal Point of Sale, 1.69% with SumUp on pay as you go or 0.99% on its £19-a-month plan, 1.2% with Dojo below £100,000 a year of card takings, and from 1.3% with Atoa, which also takes Pay by Bank from 0.7% on the same terminal.
What is the contactless limit in the UK?
There is no longer one fixed limit. Since 19 March 2026 the FCA has let banks and payment providers with strong fraud controls set their own contactless limits in place of the old £100 cap, and it expects most to keep their existing limits for now. The customer’s bank sets the limit, and a payment above it falls back to chip and PIN.
Can I accept NFC payments on my phone?
Yes, through a provider that offers tap on phone, such as Apple’s Tap to Pay on iPhone, which Square, SumUp, PayPal Point of Sale and Dojo list on their UK pricing pages. Atoa does not turn your own phone into a card reader: customers tap on the Atoa terminal, or scan a QR code to pay from their Bank app.
Does an NFC terminal accept Apple Pay and Google Pay?
Yes. Apple Pay and Google Pay use NFC between the phone and the terminal, and EMV contactless terminals are built to accept NFC-enabled phones and watches as well as contactless cards. The Atoa terminal takes Apple Pay, Google Pay and any NFC phone alongside Visa, Mastercard and American Express cards.
Is Pay by Bank an NFC payment?
No. With Pay by Bank the customer scans a QR code on the Atoa terminal or a stand and approves the payment in their own Bank app, so nothing is tapped and no card is involved. It costs from 0.7% in person ex VAT, against card rates from 1.3%, and cannot be charged back.
Sources
- NFC Forum, NFC technology: technical overview, checked 27 September 2026
- EMVCo, EMV Contactless Chip and EMV Payment Tokenisation, checked 27 September 2026
- Apple, Apple Pay security and privacy overview, published 27 April 2026, checked 27 September 2026
- Financial Conduct Authority, Greater flexibility to be given for setting future contactless limits, 19 December 2025, and Handbook Notice 136, December 2025 (changes in force 19 March 2026)
- UK Finance, UK Payment Markets 2025, summary (2024 data)
- Atoa, card machine and pricing, checked 27 September 2026
- Provider pricing pages, checked 27 September 2026: Dojo, SumUp, Square, PayPal Point of Sale
SHARE ARTICLE
Share link copied!