Ready to get started?
Easily integrate next-generation payments and financial data into any app. Build powerful products your customers love.
SHARE ARTICLE


 Share link copied!
Atoa is a payments provider, not a tax adviser. This page explains how card fees are treated so you can check your own invoices and have a sharper conversation with your accountant.
The question usually arrives from the bookkeeper. The merchant statement shows £1,840 of card fees for the month, there is no VAT line on it, and Xero wants to know which tax rate to post it under. Half the answers online say card fees carry 20% VAT. The other half say financial services are exempt. Both are right about something, and neither tells you how to find out which applies to the invoice in front of you.
This page does. It explains why two providers can charge the same percentage and treat VAT differently, how to read what yours is doing, what you can reclaim, what you can deduct, and the one number HMRC cares about that most merchant statements hide. We handle payments for a living; the rules below are HMRC’s, and your accountant has the final word.
Why the answer is “it depends who bills you”
UK VAT law exempts financial services, and that exemption covers the transfer of money. When a bank or a card acquirer processes your card payments and moves the funds to your account, HMRC treats the merchant service charge as an exempt supply, so no VAT is added (HMRC VAT Finance Manual).
But a lot of what sits between your till and your bank is not the transfer itself. Payment gateways, terminal rental, PCI compliance fees, virtual terminals, software subscriptions and “card handling” services are technology or administration, not finance, and they are standard-rated at 20%. The courts have drawn that line more than once, most visibly in the Bookit and National Exhibition Centre cases on card handling fees and the DPAS ruling on payment plan administration, and HMRC’s guidance followed (The VAT People on card handling fees; Crowe on exempt payment processing).
So the same 1.5% can appear on two invoices as £150 with no VAT, or £150 + £30 VAT, depending on whether the supplier is acting as the acquirer or as a technology layer over someone else’s acquiring. Most modern providers are the second kind.
How to read your own invoice
You do not need to know your provider’s regulatory status. You need to look at three things on the invoice or statement.
Is there a VAT line? If the fee is shown “+ VAT” or the statement carries a VAT amount and the supplier’s VAT number, it is standard-rated and, if you are VAT-registered and make taxable sales, reclaimable as input tax. If there is no VAT line and the supplier is UK-based, the fee is being treated as exempt: there is nothing to reclaim, and the whole fee is a cost.
Where is the supplier billing from? Several large providers invoice UK merchants from Ireland, the Netherlands or Luxembourg. There will be no VAT on the invoice, but that does not make it exempt: it falls under the reverse charge. You declare the 20% as output tax on your VAT return and, if you are fully taxable, reclaim the same amount as input tax in the same return. Net effect nil, but it must be recorded, and a partially exempt business (a dental practice with NHS income, say) cannot reclaim all of it.
Are there separate lines for rental, gateway or PCI? Those are almost always standard-rated even when the transaction fee is exempt. A statement with one blended number may be hiding both treatments inside it; ask for the split.
What the main UK providers do
The table shows how each provider presents VAT on its published UK fees, checked on 25 September 2026. Rates change; the provider’s own pricing page is the reference.
| Provider | Published fee (in person) | VAT shown on fee | Billing entity | What it means for you |
|---|---|---|---|---|
| Bank acquirer (Barclaycard, Lloyds Cardnet, Elavon, Worldpay) | Quoted, typically 0.4%–1.75% | Usually none on the merchant service charge; VAT on terminal rental and PCI | UK | Fee is a cost in full; reclaim VAT on rental and PCI only |
| SumUp | 1.69% pay-as-you-go; 0.99% on Payments Plus (£19/month) | None on transaction fees; plan fees shown excl. VAT | UK (SumUp Payments Ltd, FCA 900700) | Fee is a cost in full; reclaim VAT on the monthly plan only |
| Square | 1.75% in person; 1.4% + 25p online | None stated on transaction fees | UK (Squareup Europe Ltd, FCA 900846) | Treat as exempt payment service; no reclaim |
| Zettle (PayPal) | 1.75% | None stated | Luxembourg | Reverse charge likely |
| Stripe | 1.5% + 20p online | None on the processing fee | Ireland (Stripe Payments Europe Ltd) | Exempt payment service; if your accountant applies the reverse charge, net effect is nil |
| Dojo | 1.2% blended under £100,000 annual card turnover; custom above | None on the transaction fee; VAT on card machine purchase or monthly plan | UK (Paymentsense Ltd) | Split treatment: fee is a cost in full, reclaim VAT on hardware and plan |
| Atoa | Pay by Bank from 0.7% in person, 0.7% + 20p online; UK domestic cards from 1.3% in person, 1.3% + 20p online. All fees quoted ex VAT; rates fall with volume | Yes, 20% on the invoice | UK | Reclaim in full if VAT-registered and fully taxable |
Atoa’s fees are quoted ex VAT because Atoa initiates a bank payment on your behalf under its FCA payment initiation permission (FRN 1007647) and provides the software around it; it is not acting as a card acquirer (card payments through Atoa are acquired by Rapyd, FRN 900688). The VAT is on the invoice, with Atoa’s VAT number, and a VAT-registered business reclaims it. Starting rates are 0.7% for Pay by Bank and 1.3% for UK domestic debit and credit cards in person, and 0.7% + 20p and 1.3% + 20p online; both fall as volume rises.
What VAT does to the real cost of a fee
This is the part nobody puts in a table. For a VAT-registered business that makes taxable sales, a fee quoted “+ VAT” costs exactly the headline rate, because the VAT comes back on the return. A fee quoted with no VAT costs exactly the headline rate too. So the comparison is simple: compare the ex-VAT numbers.
For a business that cannot reclaim all its VAT, the picture changes. A partially exempt business or one under the £90,000 registration threshold pays the VAT for real, so 0.7% + VAT is 0.84% to them.
| Monthly card sales £100,000 | Fee | VAT on fee | Reclaimable? | True monthly cost (fully taxable business) | True cost (cannot reclaim) |
|---|---|---|---|---|---|
| Acquirer at 1.2%, exempt | £1,200 | £0 | n/a | £1,200 | £1,200 |
| Facilitator at 1.69%, no VAT | £1,690 | £0 | n/a | £1,690 | £1,690 |
| Facilitator at 1.5% billed from Ireland | £1,500 | £300 reverse charge | Yes | £1,500 | £1,800 |
| Atoa Pay by Bank 0.7% + VAT | £700 | £140 | Yes | £700 | £840 |
The lesson for a finance lead: a provider advertising “no VAT” is not cheaper; it is exempt, which means there was never anything to get back. Put every quote on an ex-VAT basis and compare those.
Are card processing fees tax deductible?
Yes. Card processing fees, terminal rental, gateway and PCI charges are all ordinary business expenses, wholly and exclusively for the trade, so they reduce the profit on which Corporation Tax (25% main rate, 19% for profits under £50,000) or Income Tax is calculated. The same is true of Pay by Bank fees. Post them to a cost-of-sales or bank-charges account, not to a reduction in sales, for the reason in the next section.
The deduction is the net fee if you reclaimed the VAT, and the gross fee if you could not. A business that cannot reclaim VAT deducts the £840 in the table above, not the £700.
The number HMRC actually looks at: gross, not net
Every card and Pay by Bank payout lands in your bank net of fees. A £10,000 day arrives as £9,850. The single most common mistake in merchant bookkeeping is to post the £9,850 as sales. Your turnover for VAT and for Corporation Tax is the £10,000 the customer paid; the £150 is an expense. Posting net understates sales by the fee, every month, and it is how businesses drift over the £90,000 VAT threshold without noticing.
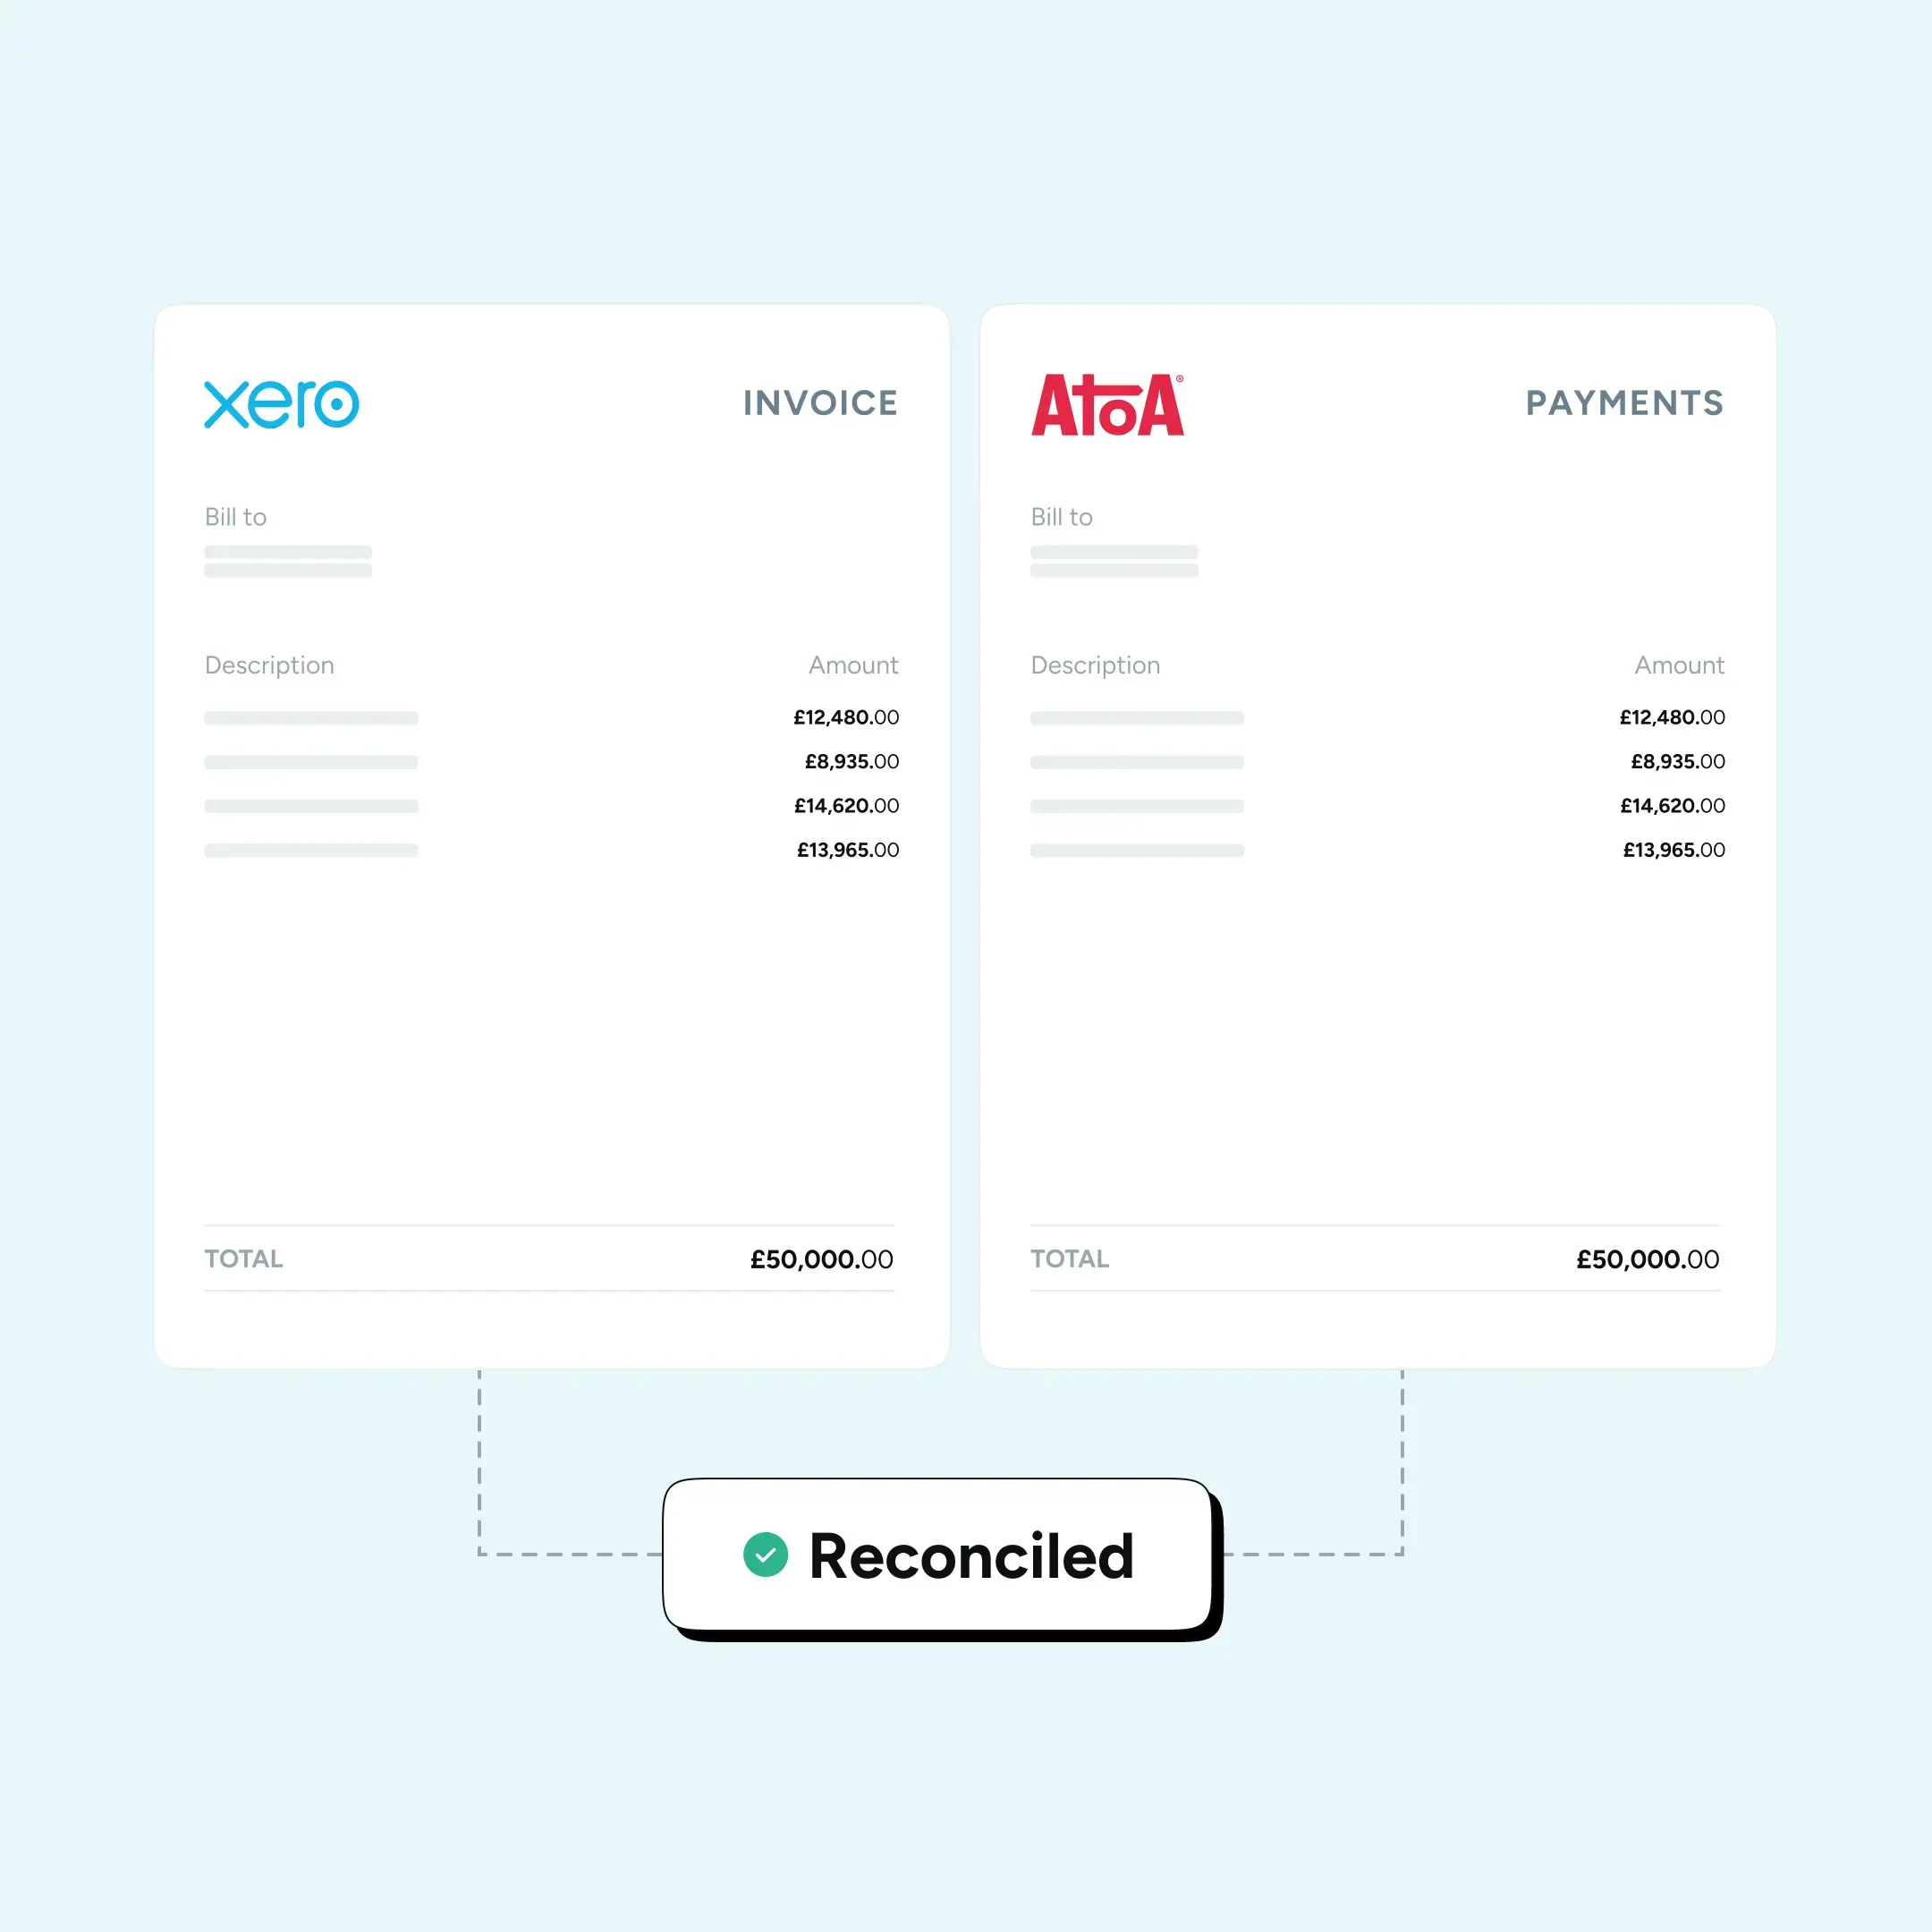
HMRC expects transaction-level settlement reports that reconcile gross sales, fees, refunds and chargebacks to each payout, not just bank statements. This is where the payment provider earns its keep: Atoa’s Xero, QuickBooks and Sage integrations post the gross sale and the fee as separate lines, so the reconciliation is done before the bookkeeper opens the file (how the Xero integration works).
Can you charge customers a fee to cover it?
Not on consumer cards. Since January 2018 UK businesses cannot surcharge consumers for paying by debit or credit card, whichever channel the payment comes through (Consumer Rights (Payment Surcharges) Regulations 2012, as amended). Commercial cards and business-to-business payments are outside the ban, but the surcharge must not exceed your cost. The practical consequence is that the fee and any VAT you cannot reclaim come out of margin, which is why the ex-VAT comparison above matters.
What this means for the fee you pay
The VAT treatment is a bookkeeping question. The size of the fee is a commercial one, and the two get confused. Card fees for UK businesses typically land between 1.5% and 3.4% all in once scheme fees, acquirer margin, rental and PCI are counted (our explainer on card processing fees breaks the layers down). Pay by Bank moves money directly from the customer’s bank to yours over Faster Payments, with no interchange, no scheme fee and no chargeback, which is why Atoa can charge from 0.7% + VAT and settle in seconds (how Pay by Bank compares with card rails). Plans and current rates are on the pricing page.
A checklist for your next VAT return
- Pull one month’s merchant statements and payout reports from every provider.
- For each, note: VAT line or none; supplier country; separate rental, gateway and PCI lines.
- UK supplier, VAT shown: reclaim as input tax. UK supplier, no VAT: exempt, no reclaim. Overseas supplier, no VAT: reverse charge, boxes 1 and 4.
- Confirm sales are posted gross and fees as an expense.
- Confirm the fee lines are in an allowable expense account for the Corporation Tax computation.
- Put every provider quote on an ex-VAT basis before comparing.
Sources
- HMRC, VAT Finance Manual
- HMRC, VAT registration threshold
- HMRC, Corporation Tax rates
- The VAT People, VAT liability of card handling fees
- Crowe UK, Am I making VAT-exempt supplies if I supply payment processing?
- Payment Systems Regulator, Interchange Fee Regulation
- Consumer Rights (Payment Surcharges) Regulations 2012
- GOV.UK, Corporation Tax
Frequently asked questions
Is there VAT on credit card processing fees in the UK?
It depends on who bills you. A bank or card acquirer’s merchant service charge is usually treated as a VAT-exempt financial service, so no VAT is shown. Payment facilitators, gateways, terminal rental and PCI fees are usually standard-rated at 20%. An overseas provider’s fee falls under the reverse charge, which you account for on your own return.
Is there VAT on Atoa’s fees?
Yes. Atoa’s fees are quoted ex VAT: Pay by Bank from 0.7% in person and 0.7% + 20p online, UK domestic cards from 1.3% in person and 1.3% + 20p online, with VAT shown on the invoice alongside Atoa’s VAT number. A VAT-registered business making taxable sales reclaims it in full, so the true cost is the ex-VAT rate.
Are card processing fees tax deductible?
Yes. Card processing fees, Pay by Bank fees, terminal rental, gateway and PCI charges are allowable business expenses and reduce the profit on which Corporation Tax or Income Tax is calculated. Deduct the net fee if you reclaimed the VAT, the gross fee if you could not.
Should I record card sales gross or net of fees?
Gross. Your turnover for VAT and Corporation Tax is what the customer paid, and the fee is a separate expense. Posting the net payout as sales understates turnover by the fee every month and can push a growing business over the £90,000 VAT registration threshold without it noticing.
What is the reverse charge on payment processing fees?
When a provider based outside the UK bills you with no VAT, you declare 20% output tax on the fee in your VAT return and, if you make fully taxable sales, reclaim the same amount as input tax. The net effect is nil for most businesses but it must be recorded; partially exempt businesses cannot reclaim all of it.
Can I charge customers a fee for paying by card?
Not on consumer debit or credit cards; UK law has banned consumer card surcharges since January 2018. Business-to-business and commercial card payments can carry a surcharge that does not exceed your cost. Any VAT you cannot reclaim on fees therefore comes out of margin.
SHARE ARTICLE
Share link copied!