Ready to get started?
Easily integrate next-generation payments and financial data into any app. Build powerful products your customers love.
SHARE ARTICLE


 Share link copied!
A founder has built a marketplace, signed up sellers and received the first orders. Now comes the question of how everyone gets paid. A customer spends £200 on products from three different sellers. Each seller needs their share, alongside the platform’s commission and the delivery partner’s fee.
Who holds the money, and when does each party receive it? If the customer returns one item, whose share covers the refund? Before collecting payments, the founder also needs to understand the platform’s regulatory responsibilities.
These decisions shape the marketplace payment solution you choose. This guide explains split payments, seller payouts and when FCA authorisation may be required. It also compares provider approaches to help you find a suitable setup.
What Is a Marketplace Payment Solution?
A marketplace payment solution helps a platform collect customer payments and pay its sellers. It keeps track of each seller’s earnings and the platform’s commission.
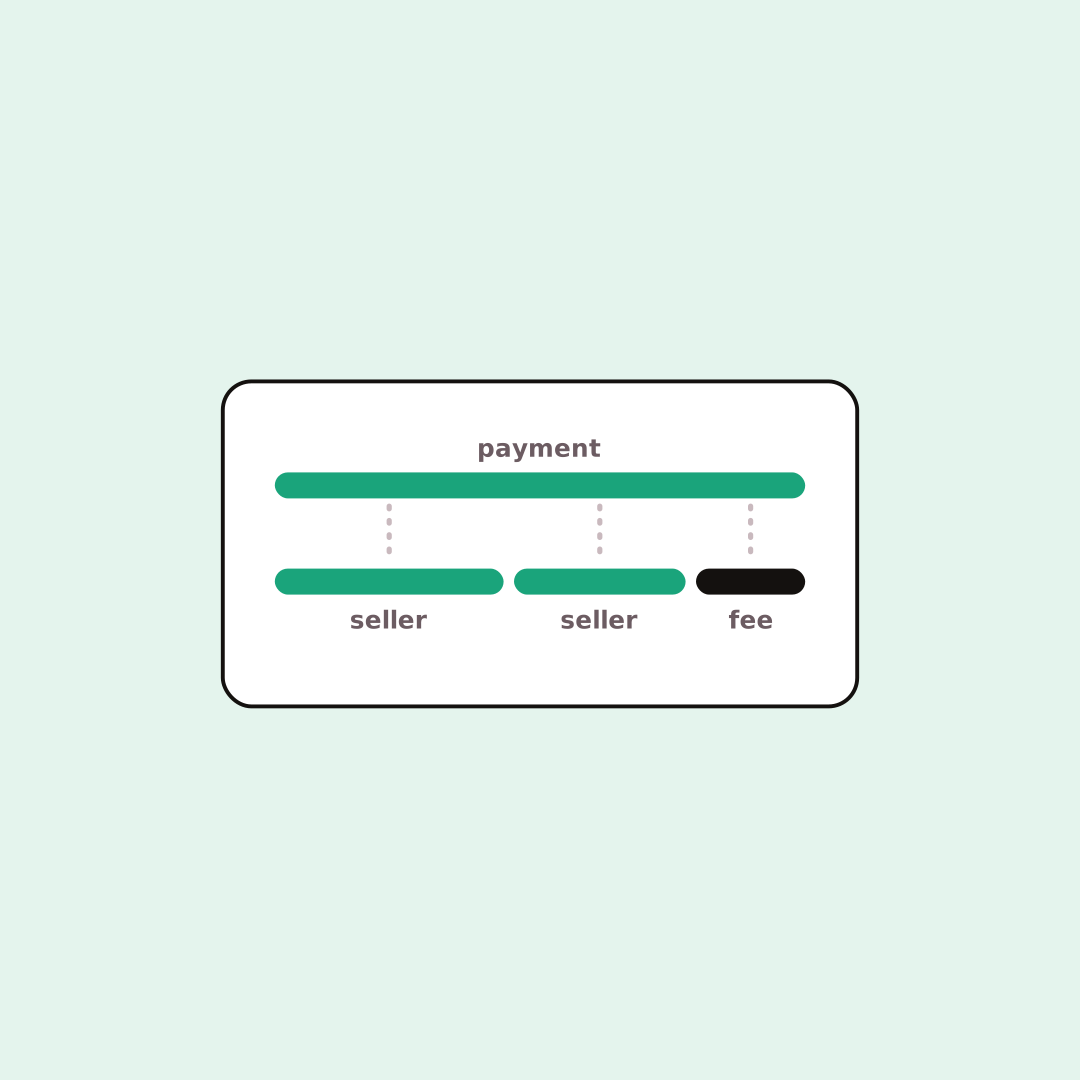
For example, a customer pays £200 through your marketplace. The provider allocates £150 to one seller and £30 to another. The remaining £20 covers a £15 platform commission and £5 delivery fee.
Beyond dividing payments, the provider helps verify sellers through identity and business (KYC and KYB) checks. Depending on the setup, funds remain in provider-managed balances until payout. The provider then transfers each seller’s available funds according to the agreed schedule.
This gives your platform a record of who earned what and when they were paid. It also helps your team track refunds and adjust the amounts owed.
How Do Split Payments Work?
Split payments divide a customer’s payment between sellers and other agreed recipients. These can include your platform and a delivery partner.
When a customer pays, the provider calculates each party’s share using agreed rules. It records those amounts, then transfers available funds according to the payout schedule.
For example, a £200 order could be divided as follows:
| Recipient | Amount allocated |
|---|---|
| Seller A | £150 |
| Seller B | £30 |
| Platform commission | £15 |
| Delivery partner | £5 |
| Total | £200 |
This example excludes processing fees, refunds and taxes. The contract should explain how those amounts affect each recipient.
The provider records the allocation and pays eligible recipients according to the agreed schedule. Recording a seller’s share and transferring it to their bank are separate steps.
A split can therefore appear in the records before the seller receives a payout. Timing depends on settlement, verification, reserves and the provider’s payout rules.
What Should Marketplace Payments Cover?
The checkout is only one part of the payment process in marketplace. The team also needs to manage sellers, refunds and the records behind each payout. Here are a few important that marketplace payment solutions should cover:
Seller onboarding and verification
Providers collect information about sellers and, where relevant, their owners too. These checks are commonly called Know Your Customer and Know Your Business (KYB & KYC).
Requirements vary according to the seller’s structure, location and activities. A marketplace platform needs a clear process for collecting information and following up on missing details.
Confirm which checks the provider performs and which tasks remain with your team. Also establish what happens when a seller’s verification needs updating.
Commission and payment allocation
Each sale needs a clear breakdown of the amounts owed. The platform may charge a percentage commission, a fixed fee or both. Other deductions could include delivery charges or additional services.
Consider how the calculation changes when a buyer returns one item. A partial refund may affect seller proceeds, platform commission and processing costs differently.
Balances and payout timing
A seller’s recorded earnings can differ from the amount available for immediate payout. Funds may still be settling, or the provider may retain an agreed reserve.
Some providers track these amounts through wallets or balance accounts. Others use different settlement arrangements. Escrow has a specific contractual meaning, so the distinction matters when comparing services.
Sellers should understand when funds become available and when transfers reach their bank. The agreement should also explain who holds the money and what safeguards apply.
Refunds, disputes and reporting
A refund becomes more complicated when an order involves several sellers. If one item is returned, the repayment needs to match that seller’s original allocation. Records should show what happens to commission, delivery charges and processing fees.
Card disputes also need a clear division of responsibility. Establish who gathers the evidence and who covers any resulting loss.
Payment reports should connect each order with its fees, refunds and seller payouts. That allows the finance team to explain what each seller received and why.
Do UK Marketplaces Need FCA Authorisation?
A platform providing regulated payment services may need FCA authorisation or registration. The assessment depends on its activities, contracts and control over funds.
Receiving buyer money before passing it to sellers deserves particular attention. A marketplace label alone tells you little about the regulatory position.
The FCA recommends independent advice where a business is unsure about its activities. Review the payment flow before committing to an integration.
What is the commercial agent exclusion?
The commercial agent exclusion applies to qualifying arrangements under the Payment Services Regulations 2017.
The agent must have formal authority to negotiate or conclude a sale. It must act for either the buyer or seller, rather than both.
Simply collecting money provides an insufficient basis for relying on this exclusion. The contract and the platform’s actual activities must support the arrangement. The FCA explains these conditions in its commercial agent guidance.
What arrangements can a platform consider?
Depending on the business model, the options marketplace may include:
- Obtaining the appropriate authorisation or registration.
- Acting as a registered payment-services agent of a regulated principal.
- Using a provider arrangement that keeps the platform outside regulated payment activities.
Payment-services agents operate under a specific framework. An appointed representative arrangement for other financial activities is a different route. Check the firm’s status and permissions on the FCA register.
Using a regulated provider still requires a review of your platform’s responsibilities. The provider’s licence covers its permitted activities, while your role needs separate assessment.
Which Providers Support Marketplace Payments?
Several providers offer tools for seller onboarding, payment allocation and payouts. Their services differ by country, integration and commercial agreement.
The comparison below describes their approach rather than ranking them.
| Provider | Marketplace payment approach |
|---|---|
| Ryft | Supports marketplace payments, seller onboarding and automated payment splits. |
| Stripe Connect | Uses connected accounts to manage payments between platforms and sellers. |
| Adyen for Platforms | Provides user onboarding, split instructions, balance accounts and payouts. |
| Mangopay | Uses wallet-based infrastructure for collecting, allocating and paying out funds. |
| PayPal multiparty payments | Supports seller onboarding, partner fees and marketplace checkout arrangements. |
Note that these descriptions reflect the providers’ published product information online. Availability and specific features depend on the account and integration.
Compare providers against your actual transaction before confirming. A platform selling across countries will have different requirements from a domestic service marketplace.
What Do Marketplace Payments Cost?
The processing rate is one part of the total cost. Depending on the provider, additional charges may apply to accounts, payouts or currency conversion.
Review the charges attached to:
- Customer payments, including fixed and percentage fees.
- Seller accounts, verification and platform features.
- Payouts, refunds and card disputes.
- International cards and currency conversion.
A split can create several accounting entries within the provider’s system. Whether each entry attracts a charge depends on the pricing agreement.
Use realistic orders when comparing quotes. Include purchases involving several sellers, partial refunds and overseas payouts.
Payout frequency can also affect costs where a provider charges per transfer. Compare daily and weekly schedules against sellers’ cash-flow needs.
How Do Cross-border Payments Affect a Marketplace?
Cross-border payments involve parties or payment arrangements spanning different countries. For marketplaces, buyer acceptance and seller payouts need separate consideration.
A provider may accept an overseas customer’s card while supporting fewer seller payout countries. Check both sides before inviting international sellers onto the platform.
Currency conversion also needs a clear owner. Establish who chooses the conversion currency and who pays the exchange margin.
Payout timing varies by currency, banking route and local processing hours. Confirm expected timings for each country rather than applying one estimate everywhere.
International sellers may need different identity documents or business records. Build those requirements into onboarding so sellers understand what to provide.
The currencies, payment routes and fees involved in cross-border online payments should inform your seller terms and pricing.
When Your Platform Sells Directly to Customers
Some platforms purchase goods from suppliers and resell them to customers. In this model, the platform may be the seller under the customer contract.
Customer payments then represent the platform’s own sales revenue. Supplier payments are handled separately through its purchasing arrangements.
This model may suit standard payment acceptance rather than marketplace splits. The contracts and actual business activities must support that distinction.
A website’s appearance alone establishes little about who legally makes the sale. Confirm who invoices the customer, handles returns and carries the seller’s obligations.
How this applies to B2B payments
B2B describes transactions between businesses rather than a particular platform structure. A B2B platform could operate as a reseller or connect independent suppliers with buyers.
A reseller usually collects its own invoices and pays suppliers separately. A marketplace may collect payments involving several independent sellers.
Order values, invoice terms and reconciliation needs also influence the payment method. Comparing B2B payment solutions helps clarify those collection requirements.
Where Atoa fits
Atoa supports businesses collecting payments for their own goods and services. Its services include card payments and Pay by Bank.
Pay by Bank costs 0.7% plus VAT. Customers approve the payment through their banking app, with funds typically arriving within seconds.
Businesses can collect payments through an online checkout, payment link or in-person QR code. Card payments provide another option for customers who prefer paying by card.
Atoa’s role here is direct payment acceptance. A setup requiring automatic splits, marketplace seller balances and third-party payouts needs a dedicated marketplace service.
Pay by Bank operates outside card-scheme chargebacks. Refund obligations, customer rights and applicable bank-payment protections still apply.
How Payments Work at Physical Multi-vendor Sites
Food halls, markets and concession-based stores can use several payment arrangements. The right choice depends on who sells to the customer and receives payment.
Each vendor collects its own payments
Each trader can accept payment directly into its own approved account. The site operator might charge rent or invoice traders for commission separately.
This approach keeps each vendor’s takings linked to its own business. Provider reporting and access permissions determine what the operator can view.
Where Atoa is being considered, confirm eligibility for each vendor separately. Also confirm reporting access before promising a shared view across independent businesses.
Customers use a central checkout
A central till can collect purchases involving several independent vendors. That arrangement may require allocation, seller payouts and a regulatory assessment.
Alternatively, the site operator may act as the actual seller. Its supplier payments would then follow the terms of that business model.
The physical location changes the checkout experience, while the contractual role determines the payment requirements. A food hall can face the same fund-flow questions as an online platform.
How to choose the right marketplace payment solution
A useful comparison begins with one complete customer order. Follow it from checkout through fees, refunds and the final seller payout.
Check whether the provider supports your seller countries and business categories. Then compare onboarding requirements, payout timing and responsibility for disputes.
Give your finance team sample reports before committing to an integration. They should be able to reconcile every payment and explain each deduction.
For developers, the important questions include integration work, payment-status updates and failure handling. Test partial refunds and failed payouts as carefully as successful purchases.
Finally, document the regulatory arrangement and each party’s responsibilities. Product features and legal responsibilities need to agree with the payment flow.
Conclusion
The right marketplace payment setup follows the relationship between buyers, sellers and your platform. Establish who makes the sale, controls funds and handles refunds first.
Then compare providers using actual orders, seller locations and payout requirements. Platforms collecting their own sales may need standard card and bank-payment acceptance. Platforms distributing proceeds between independent sellers need the corresponding marketplace tools and regulatory arrangement.
Frequently Asked Questions
Can one checkout include purchases from several sellers?
A marketplace provider may support one checkout with allocations to several sellers. The underlying payment structure depends on the provider and integration.
Can sellers receive payments on different schedules?
Some providers support configurable payout schedules, subject to their rules and risk checks. Verification, reserves and settlement timing can affect when funds become available.
Does a marketplace need an escrow account?
The appropriate arrangement depends on the business model and provider. Some services use wallets or balance accounts, while others offer different settlement structures.
Describe the arrangement as escrow only where the contract establishes that service.
Does Atoa offer marketplace split payments?
Atoa’s services cover direct payment acceptance through cards and Pay by Bank. Platforms needing seller splits, marketplace balances and third-party payouts require a dedicated marketplace provider.
Can one payment provider serve several independent vendors?
A provider may support separate accounts for eligible vendors. Shared reporting and operator access depend on its product and permission settings.
Using one provider still requires each vendor’s business and payment arrangements to be assessed.
Does using a regulated provider settle the FCA question?
The platform’s own activities and contractual role still require assessment. Confirm which services the provider performs and which responsibilities remain with your business.
SHARE ARTICLE
Share link copied!